
What happens to U.S. workers without access to Unemployment Insurance amid economic downturns or disruptions related to AI?
Essays SEP 2, 2026
By: Megan Rivera
About the author: Alan Blinder is Gordon S. Rentschler Memorial Professor of Economics and Public Affairs at Princeton University and former vice chairman of the Board of Governors of the Federal Reserve System.
The short answer is: not much. Hippocrates offered good advice when he said “first do no harm.”
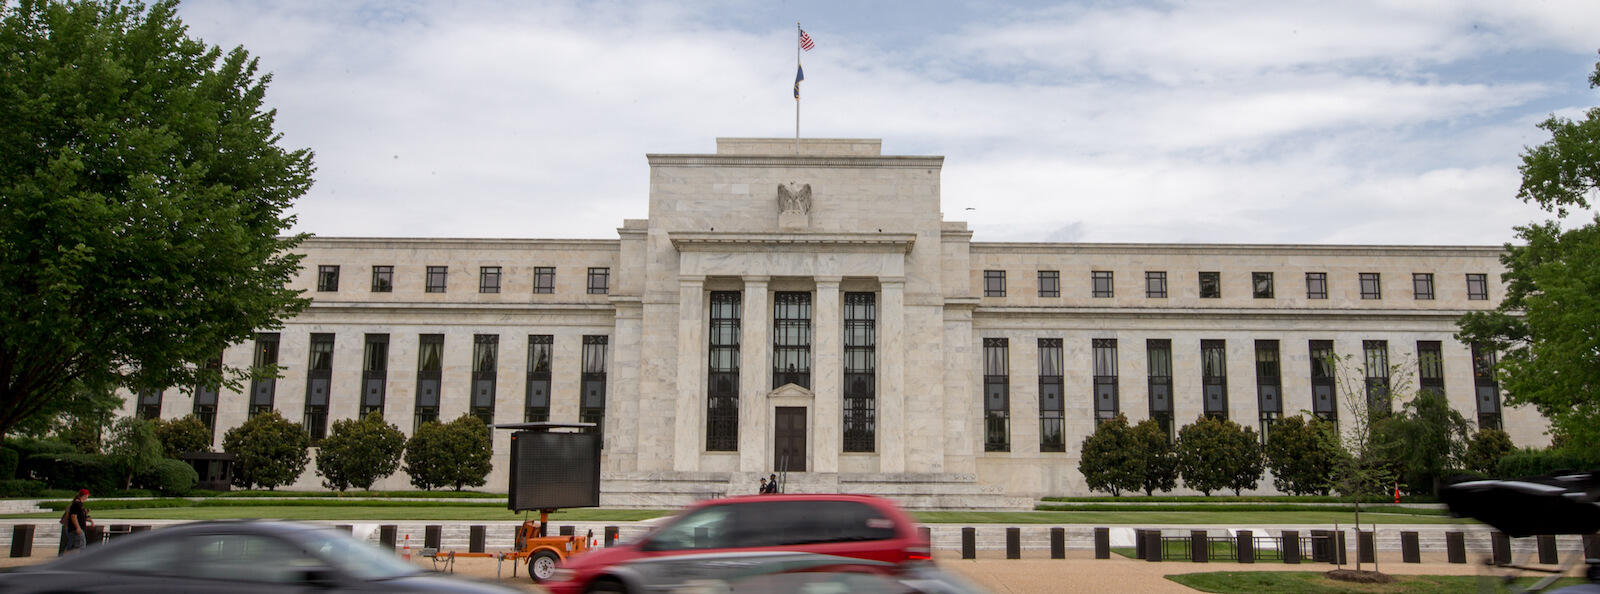
This does not mean that the Federal Reserve is perfect. Parts of its governance structure read like they date from 1913 (as they do) and could use a tune-up. But by and large, the Fed continues to perform the functions assigned to it by Congress well—even in this time of dysfunctional government—and to be genuinely non-political (see below). The next president should not upset either of these apple carts.

Four points are important to understanding the independence of the Fed. All should be preserved.

I started with “first do no harm” because Congress is now considering three very bad ideas.
The new President should oppose these three anti-Fed bills, and veto them if Congress passes any of them.

According to a wise old principle, if it ain’t broke, don’t fix it. The Fed is not “broke.” So preserving the status quo is not a bad policy.
It is true that, were the Federal Reserve Act being written today rather than in 1913, it would look different in several respects. For instance, the boundaries of the 12 Federal Reserve Districts and the locations of the 12 Federal Reserve Banks would certainly be different. Those boundaries, which reflect the economic geography and political logrolling of 1913, look a little comical in 2016. But moving them is almost certainly not worth the political fight it would provoke.
Previous article: Wealth transfer taxation (opens in a new tab), Lily Batchelder
Next article: Home mortgages, Atif Mian and Amir Sufi
A better case can be made for revisiting the 1913 Wilsonian compromise between two competing visions of a central bank: one controlled by private parties (mainly bankers), the other controlled by the federal government. The Federal Reserve Act (and its 1935 amendments) split the difference by dividing power between a seven-member, politically appointed Board of Governors in Washington and 12 Federal Reserve Banks, which are joint-stock companies owned by member banks, and whose presidents are not political appointees. (They are, instead, selected by each bank’s board, just as private corporations do.) The Fed’s powerful Open Market Committee consists of the seven Washington-based governors and the 12 bank presidents (only five of whom get to vote at a time). It is odd, to put it mildly, to have men and women with no political legitimacy making national economic policy.
In increasing order of “radicalness,” the Wilsonian balance could be tilted more in the governmental direction by:
Another sensible reform would be to shorten existing term limits. Under current law, a Federal Reserve governor (including the chairman) could, in principle, serve almost 28 years. Although this has never happened, Alan Greenspan did chair the Fed for 18½ years, and William McChesney Martin served a few months longer than that. For such a powerful position, that seems too long. When he retired in 2014, Ben Bernanke did not try to set a “George Washington” precedent that two four-year terms is enough. Perhaps we should write that into law.

Should the U.S. economy encounter a recession any time soon—say, within the next two years—the old “leave-it-to-the-Fed” attitude will probably not suffice. For one thing, interest rates will still be very low, leaving the Fed limited scope for cutting rates. For another, the Fed’s balance sheet will still be huge, leaving it limited scope for further “quantitative easing”—not to mention the fact that quantitative easing probably ran into sharply diminishing returns years ago. All this is not to say that the Fed would be powerless to fight, say, a 2017 recession, but only that it will be considerably less powerful than it has been in the past, leaving the nation more vulnerable.
What to do? The obvious answer would be to deploy fiscal policy—that is, government spending and tax cuts—as was done in 2009. But, depending on the composition and attitudes of the next Congress, that might prove challenging (or impossible) politically.
So the first, and easy, policy recommendation is that the new administration should quickly formulate contingency plans for a possible fiscal stimulus and, to the maximum extent possible, seek buy-in from the congressional leadership.
That “maximum extent possible” might prove to be zero, however. So the new administration should also consider legislation that would increase the strength of the automatic stabilizers.
Essays SEP 2, 2026
By: Megan Rivera
Videos AUG 13, 2026
By: Equitable Growth
Essays AUG 7, 2026
By: Chiara Chanoi
Get updates on our latest research, event announcements, and policy insights delivered straight to your inbox. Stay connected with the leading voices on equitable growth.