


Policy
What Work Does Generative AI Do?
Essays SEP 8, 2026
By: Alexander Bick, Adam Blandin, David Deming, Tyler Schumacher
AI, Tech & Energy
Labor, Wages & Worker Power
 Browse All Resources
JUL 27, 2018
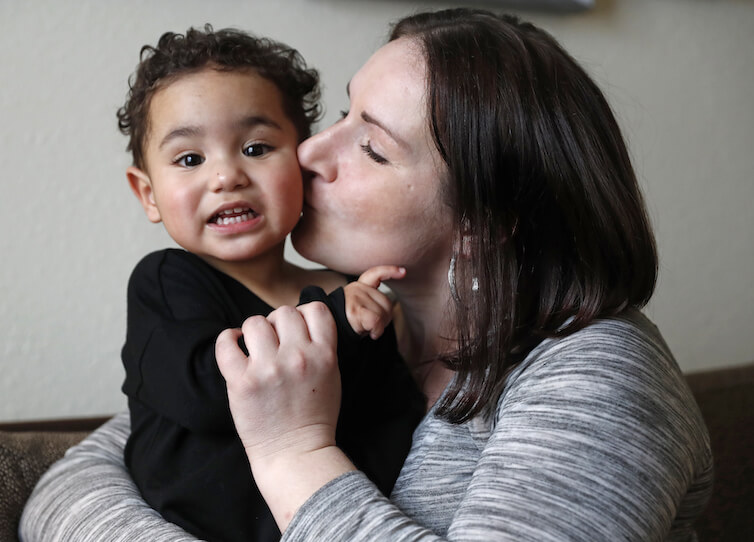
With the launch of our new website, we are reintroducing visitors to our policy issue areas. Informed by the academic research we fund, these issue areas are critical to our mission of advancing evidence-based ideas that promote strong, stable, and broad-based economic growth. Through June and July, expert staff have been publishing posts on our Value Added blog about each of these issue areas, describing the work we do and the issues we seek to address. The following post is about Family Economic Security. For previous posts on other issue areas, please go to our Value Added home (opens in a new tab).
As a raft of research (opens in a new tab) illustrates, economic growth is increasingly concentrating at the top of the U.S. income distribution—a trend beginning in the 1980s and running right through to the present day, with historically high shares of national income flowing into the pockets of those at the very, very top of the income ladder. This rise in income inequality stands in stark contrast to the period of broadly shared economic growth that characterized the U.S. economy from the aftermath of the World War II through the early 1980s.
This rise in income inequality over the past four decades was accompanied by monumental shifts in families’ economic lives. Women’s labor market participation (opens in a new tab), especially that of mothers (opens in a new tab), shot upward. At the same time, the risk-sharing relationship between firms and workers fundamentally shifted (opens in a new tab), as new forms of health insurance, retirement benefits, and other forms of nonwage compensation pushed downside economic risk (opens in a new tab) onto the shoulders of workers and their families. The result: destabilized household balance sheets (opens in a new tab) and families’ lives (opens in a new tab), problems that are not adequately mitigated by outdated public policies grounded in New Deal-era assumptions about the way people live their day-to-day lives.
The Washington Center for Equitable Growth’s Family Economic Security portfolio focuses on understanding how this shifting constellation of risks to family economic well-being is shaping both microeconomic and macroeconomic outcomes. A focus on the family as a core economic concept allows for the examination of a host of concepts that are too often relegated to the sidelines (opens in a new tab) in “serious” economic conversations. In the vast majority of both academic and policy research and analysis, the central unit for understanding economic well-being is the individual worker.
Consider the regular conversations about the health of the labor market, which is shaped by the U.S. Bureau of Labor Statistics’ monthly jobs report (opens in a new tab) on individual unemployment rates and employer-based reports on individual jobs created. These numbers are obviously important (opens in a new tab), yet understanding the health of the economy requires putting each of those individual data points in the context of the economic relationships that shape the actual, lived experience of the individuals in question. And as hundreds of millions of Americans know from experience, nearly every worker is embedded in a family of some variety.
Understanding individual workers’ economic well-being requires understanding them in the context of their families. This is all the more true as family structures (opens in a new tab) in the United States continue to evolve. A family perspective also allows for a multigenerational lens. We know that children’s long-term outcomes are shaped in important ways by their early (opens in a new tab) experiences (opens in a new tab), but the impact of family may matter well beyond childhood (opens in a new tab). For instance, access to parental wealth may shape risk preferences in ways that impact innovation and entrepreneurship for adults. And the needs of elderly parents (opens in a new tab) may fundamentally shape adult children’s economic well-being.
The idea of the family as a central focus for understanding broader questions of national economic importance is not new. Nobel Prize winner Gary Becker introduced the concept (opens in a new tab) to mainstream economics, illuminating the idea of the family’s role in developing human capital through investments in children, the central importance of family-based consumption decisions for shaping both economywide demand and family well-being over time, the division of time between market work and household work, and the maintenance and development of adult human capital. More recent contributions include MacArthur Fellowship award-winner Nancy Folbre’s pathbreaking work (opens in a new tab) on the central role of care work and other nonmarket labor in shaping the economic well-being of families, communities, and economies as a whole.
A growing body of research suggests that stabilizing families’ economic lives is good not only for the economic well-being of individual beneficiaries but also for the broader U.S. economy. The rise in women’s labor market participation, for example, creates a new set of challenges (opens in a new tab) for many families, as women’s traditional role as family caregivers—for babies but also for elder relatives—is chaotically upended. Yet research (opens in a new tab) on the consequences of providing paid family and medical leave show that well-designed policies may improve the outcomes of the children (opens in a new tab) and elders (opens in a new tab) receiving childcare and elder care, boost women’s long-term labor market outcomes (opens in a new tab), and decrease the likelihood that recipients need other public benefits (opens in a new tab) such as supplemental nutrition assistance, Temporary Assistance for Needy Families, and Medicaid.
Equitable Growth’s paid leave research and analysis is illustrative of a broader set of underlying questions that shape our approach to advancing evidence-based ideas and policies that promote strong, stable, and broad-based economic growth. We want to better understand how structural economic shifts and demographic change affect the risks to family economic stability. How have public policies evolved—or failed to evolve—to mitigate these risks? What do these risks mean for the health of the U.S. economy as a whole? And what kinds of policy interventions are best suited to solving these challenges, particularly in the context of a rapidly changing labor market where the future of work may be organized very differently—with dramatically different consequences for families depending on their places on the U.S. income and wealth ladders. This is the core set of questions that our Family Economic Security portfolio seeks to answer.
Essays SEP 8, 2026
By: Alexander Bick, Adam Blandin, David Deming, Tyler Schumacher
Working Papers SEP 8, 2026
By: Alexander Bick, Adam Blandin, David Deming, Tyler Schumacher

Essays SEP 2, 2026
By: Megan Rivera
Get updates on our latest research, event announcements, and policy insights delivered straight to your inbox. Stay connected with the leading voices on equitable growth.


