Skip to content
Browse All Resources
Blog

JAN 14, 2021

Public investments in social insurance, education, and child care can overcome market failures to promote family and economic well-being

Public investments in social insurance, education, and child care can overcome market failures to promote family and economic well-being

Abstract

This essay is part of Boosting Wages for U.S. Workers in the New Economy (opens in a new tab), a compilation of 10 essays from leading economic thinkers who explore alternative policies for boosting wages and living standards, rooted in different structures that contribute to stagnant and unequal wages. The authors in the new book demonstrate that efforts to improve workers’ access to good jobs do not need to be limited to traditional labor policy. Policies relating to macroeconomics, to social services, and to market concentration also have direct relevance to wage levels and inequality, and can be useful tools for addressing them. 

To read more about Boosting Wages for U.S. Workers in the New Economy 20 and download the full collection of essays, click here.


Overview

Families in the United States are, to a large extent, left to fend for themselves. They must provide for their children’s early child care and college education. They must also save for, or purchase, private insurance against a range of risks, including job loss, old age, and care needs—that is, if they can afford to do so. Economic theory, plenty of evidence, and the long experiences of many families all show that the lack of protection against these risks burdens families, which greatly need social insurance protection in these areas. This is combined with rising costs of healthcare, child care, higher education, and long-term care, and the rise of fissured work that has eroded workplace benefits, leaving families’ economic positions even more precarious. A greater public role would enhance both economic efficiency and family well-being.

We argue for a larger public role in protecting families through the public provision of care and social insurance. Government needs to play a larger role in insuring against certain types of risks that individuals and families face, including greater Unemployment Insurance protections alongside old age insurance, health insurance, and long-term care insurance. Government also needs to do more to support families in the raising and educating of children during their early childhood years and when they go to college.

The high costs that families bear in financing these economic necessities are not necessary but arise from market failures. Addressing these market failures through greater public investments would be cost effective and boost family well-being. The federal government can provide social insurance protections at a much lower overall cost, and by removing major risks from families’ own balance sheets, enable families to stretch their market earnings further, enhancing their economic security. In effect, the government provision of these social protections would increase the real value of wages, allowing for better and more secure living standards at any given market wage.

In this essay, we first present the evidence for why expanded public social insurance programs would improve families’ living standards and the broader U.S. economy, and then turn to the reasons why increased public support for early childhood care and college education would deliver greater family well-being. While disparate, all of the policy proposals presented in this essay share a unifying feature: They all would dramatically improve family well-being, much more than the amount that these public investments would cost to provide.

Expand public social insurance programs to improve families’ living standards

The private purchase of homeowners or renters insurance, car insurance, and life insurance is rightly seen as an essential part of a middle-class family’s budget, and there are well-developed markets for these risks. However, families also face many risks that are not easily insured against in private marketplaces. They cannot buy fairly priced insurance against the possibilities of losing their jobs in recessions, of outliving their savings, or of contracting a serious illness.

Most families also cannot afford to buy insurance against the enormous potential expense of long-term care in old age. While families might want to purchase these types of insurance, it is highly unlikely that private insurance markets can be made to function well in any of these areas, even with aggressive regulation, suggesting a natural role for public provision.

The absence of insurance leads to large uncovered risks and, often, to costly responses. Families are forced to juggle the competing imperatives of saving for retirement and saving for health emergencies and long-term care in old age. Many forego needed medical care and, when they encounter serious illnesses, declare bankruptcy due to an inability to pay the bills.

These uncovered risks also distort other aspects of families’ lives. Health insurance considerations become an important part of job choices, overriding other concerns. The resulting “job lock” depresses wage growth. Inadequate Unemployment Insurance means that a recession risks pushing families into financial ruin, quickly wiping out savings and standards of living. Later in life, many find themselves intentionally spending down their savings in order to qualify for Medicaid coverage for long-term care.

There has long been a recognized role for the public sector in the provision of social insurance where private insurance markets do not function well. An example is disability insurance. Those who become disabled often lose their livelihoods, but information asymmetries make it very difficult to purchase disability insurance on private markets. Where insurance is available, underwriters often require extensive medical exams and refuse to write insurance for those with preexisting conditions. Through the Social Security Disability Insurance, or SSDI, and Supplemental Security Insurance, or SSI, programs, the government provides insurance to all, supplying monthly income to the disabled through (in the case of SSDI) premiums levied on the healthy.

Unfortunately, our existing social insurance system, while important, does not adequately cover many of the risks described above, with major consequences for families’ financial health and well-being. Without insurance, even prosperous families lack economic security. Publicly provided social insurance can protect them from these risks and thereby promote security. Specifically, we advocate expansions of public social insurance to better cover the risks of:

  • Unemployment
  • Longevity
  • Adverse health events
  • Long-term care

We detail the importance of each of these investments in turn. In each area, an expansion of our traditional understanding of social insurance would dramatically improve the well-being of the typical family. In many cases, it would enable them to pursue higher wages through smoother operation of the labor market. It would allow them to live more comfortably and securely for any given market wage. And it would provide the growth in living standards that wages themselves have not been able to achieve in recent decades. In each case, there is a straightforward program that would provide the support that families need.

Unemployment Insurance

Workers who lose their jobs need to finance consumption—food and clothing, heating and air conditioning, housing and transportation—until they find new jobs, generally with very limited ability to borrow against future income. An 85-year-old joint federal-state program provides Unemployment Insurance to workers, financed by payroll taxes. To limit coverage to those who are truly involuntarily unemployed and to avoid moral hazard, Unemployment Insurance benefits are limited to those laid off from their jobs through no fault of their own. Those who quit or are fired for cause are generally not eligible.

Another measure taken to restrict moral hazard is the limit of time placed on benefits. These time limits typically run for 26 weeks, on the theory that anyone actively looking for work should be able to find a new job before their benefits run out. The idea here is to balance moral hazard against the need for insurance.279 The program also includes job search requirements for those receiving benefits.

This insurance is quite valuable to workers, as the alternative is that all workers would need to maintain substantial savings against the possibility of losing their jobs. But many workers with irregular employment histories do not qualify for Unemployment Insurance benefits when they lose their jobs, nor do workers classified by their employers as independent contractors. The result is that a large share of workers who lose their jobs do not receive unemployment benefits.

Moreover, the uniform program described above does not address systematic differences in the availability of jobs. The chance that a worker will be able to find a job within 26 weeks, even with diligent search, varies enormously over the business cycle. As a consequence, Unemployment Insurance recipients in weak labor markets are much more likely to exhaust their benefits. This indicates that the moral hazard-insurance trade-off needs to be recalibrated during these times, allowing for longer benefit durations and more generous benefits when jobs are scarcer. This should be automatic and should last as long as the economy remains weak.280 

Such a policy offers benefits beyond basic risk protection. First, unemployment benefits stabilize demand in the broader economy by boosting consumption among those with high propensities to spend. Automatic extensions would ensure that public insurance spending arrives when the economy needs the additional demand, not afterward. Second, the moral hazard argument for encouraging unemployed workers to actively search for jobs by limiting the duration of benefits is much attenuated in recessions because there are “congestion effects” in job search—one worker’s more diligent search just makes it harder for the next to find a job.281 Third, benefit extensions mean that unemployed workers are not forced to desperately accept any job offer that comes along. They can take the time to search for a position that is a good fit (opens in a new tab). This increases workers’ bargaining power and improves job matching, allowing workers to find the roles where they can be most productive and can earn the highest pay.282

A package of modernized eligibility requirements that ensures that much larger shares of displaced workers are eligible for benefits, combined with automatic triggers that extend benefits and increase generosity in poor economic conditions, would help the already-successful program do more to support our modern economy.

Old age insurance

It is hard for most families to save enough during their careers to support adequate consumption during retirement. This is made harder because it is impossible to predict just how much savings people will need—the unpredictability of lifespans and of investment returns creates substantial risk. The only way people can protect themselves is by saving much more than they will likely need, to avoid running out of money at the ends of their lives. This precautionary saving reduces families’ economic well-being across generations.283

People would be much better off with insurance that guaranteed them a stable income for as long as they live. There is no real moral hazard problem here, and such insurance products exist: Annuities are financial products offered in private marketplaces that provide guaranteed income for the remainder of one’s life. Annuity markets generally function poorly, however, for reasons that are not entirely understood but include adverse selection (the tendency for those who know they will live longer to buy more insurance, raising the price insurers must charge), shortcomings of insurer regulation, and the substantial complexity of the products on offer.284 As a consequence, annuities are generally priced well above their actuarial value, and few people buy them.285

The resulting market failure creates a clear and long-recognized public need. Since 1935, Social Security Retirement Insurance provides a mandatory retirement annuity to all American workers, with some modest redistribution from high-earning workers to low-earning ones and from later to earlier cohorts. But Social Security was designed to be just one part of what was intended as a three-legged stool, with private pensions and individual savings providing the other legs.

Over the past six decades, one of these legs has nearly disappeared (opens in a new tab) as these days, only one-fifth of full-time, private-sector workers are covered by a defined-benefit pension.286 The third leg—individual savings—has never functioned well. Less than 60 percent of those approaching retirement have any retirement savings, and more than half of those have saved less than $100,000, not nearly enough to last through a long retirement. Moreover, those who do save still face uncovered risks from financial market volatility, as well as the risk of outliving their savings.

Social Security is the crown jewel of our current social insurance system. But precisely because private pensions and individual savings have proven unsuccessful as complements, we propose expanding the Social Security annuity to cover a much larger share of expected retirement consumption. Social Security should be seen as it functions for many households: as the basis for retirement consumption, not merely as one equal part among three.

Even an expanded universal retirement benefit, however, would not meet all retirement needs. We propose to combine an expansion of the base benefit with an optional public annuity, structured as an option to top up one’s Social Security benefits through voluntary additional contributions. Those who make these contributions would receive higher guaranteed benefits, administered through the existing Social Security system. This would, of course, benefit only those who could afford to make such contributions, but for them, it would be a far superior way to save than existing defined-contribution vehicles such as 401(k)s, insulating them from market and longevity risks that they are poorly suited to bear.

Health insurance

Medical care absorbs an ever-growing share of national expenditures. Progress in medical science makes it possible to treat a wide range of ailments that were previously untreatable, though often at a high cost. Given these high costs, health insurance is essential to economic security. Yet private health insurance markets rarely work well.

One problem is that people are often unable to purchase insurance for the most serious risks that they face. Before they were banned by the Affordable Care Act, preexisting conditions exclusions meant that many people, even those with insurance, were uncovered for major potential expenses. Even with the ACA’s protections—which may be invalidated by a pending Supreme Court decision—there are other ways for insurers to shift risk. Employers may negotiate for less-comprehensive insurance to save costs, or insurers may charge high premiums to employers with workers at risk of high expenses.

A second problem is that the correct care is not easily observable and often depends on doctor discretion. This creates what economists call a principal-agent problem, in which the interests of medical providers (who earn more when more care is provided) do not always align either with those of patients or those who are paying the bills. This leads to extensive controls on care usage, frequent denial of coverage for legitimate claims, and enormous hassles for policyholders.

The end result is that, absent very strict regulation, many workers go without insurance altogether, and those who have insurance still face large risks of being bankrupted by charges that insurance companies deny.287 This can create what is known as an adverse selection spiral, where only those with the highest prospective costs buy insurance and, as a result, insurers must raise prices, further discouraging those with below-average costs.

Third, the decision to forego insurance is not a purely private one. Health insurance and healthcare generate “positive externalities” to society. Healthier citizens are more productive, and those without health insurance may ultimately depend on safety net programs when they get sick.288 This means that we all have a stake in ensuring that all households have access to adequate, affordable care.

All of this argues for a larger public role in providing health insurance coverage. This would have additional benefits, beyond purely reducing risk to workers. First, it would create opportunities to control costs, which, under our current system, continue to spiral upward. As these costs are largely borne by employers today, this would allow wages to rise without increasing total compensation costs. Second, under our current employer-based health insurance system, many workers, particularly those with preexisting conditions, feel unable to move (opens in a new tab) to new jobs lest they risk their health insurance coverage.289 This “job lock” impedes career progression and wage growth.

To improve our public health insurance system, we need to build on our existing successful social insurance system, anchored by Medicare, via the public provision of health insurance to a much wider swath of workers and their families. This would dramatically reduce the private-sector bureaucractic and transactional costs of private healthcare while ensuring universal coverage. It would remove one of the major financial risks that families face, enable more people to get the care that they need, and allow for a more flexible and dynamic labor market.

Long-term care insurance

A related risk that families face is the potential need for long-term care. Many people need labor-intensive personal care following major illnesses, as well as at the end of their lives. This is a major expense that arrives when people are least able to accommodate it. In principle, healthy people could save against possible future long-term care needs, but the range of possible outcomes is so enormous, and the variability so high, that few do this.

Private insurance markets exist but are complex, hard to understand, and badly undersubscribed. Adverse selection seems to combine with individual optimization failures—people prefer to wait until they are sick to purchase long-term care insurance, but by that point, it is unaffordable.290 They are then forced to rely upon Medicaid coverage, which provides low-quality care for those who are eligible but requires spending down one’s assets to qualify.291 The net effect is that people’s well-being in old age is at great risk, and the government still winds up bearing much of the cost.

To overcome all of these problems, policymakers should combine public health insurance with a long-term care benefit (opens in a new tab), not means tested, as Medicaid is, but available to all. Providing higher-quality, universal public coverage without requiring recipients to exhaust all savings and assets before using it would be expensive, but would much improve the well-being of those in need and those who care for those in need.292

Investing in public early child care and preschool education, and higher education

The social insurance programs detailed above would remove major risks from families. Other important, fast-growing expenses that families face are child care and education. Substantial new public investments in these areas would not only prepare the next generation of workers and their future families to be more productive members of the U.S. economy and society, but also would reduce the drag on families’ budgets, enabling families to contribute more to our economy and to enjoy higher standards of living. In this section of the essay, we’ll look first at early child care and education, and then at higher education.

Early child care and preschool education

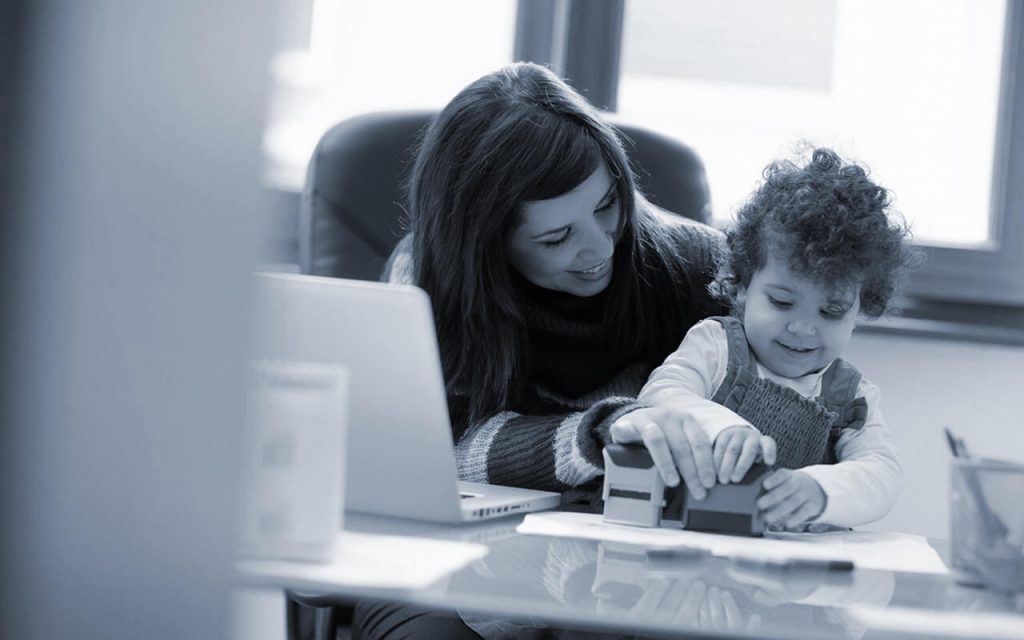
Children are very expensive, particularly in their early years. Families must provide round-the-clock care, either purchasing it at high cost on the private market or relying on a family member, who is then unable to work in the market. Moreover, while research has shown large benefits from high-quality early childhood education, this is very expensive, too. Parents must bear these costs, though most of the benefits accrue to the children, and must do so at a time in their lifecycle when they have few resources to draw upon.

The decision whether to purchase early child care and early childhood education, along with the burden of paying for it all, rests on parents today, while it is the children’s futures that are at stake. In theoretical models, families should collateralize their children’s future earnings as security for loans to finance these investments. In these models, parents may invest less in children’s education than the children themselves would, as they may not value the benefits as much.

More importantly, however, the loans needed to support this arrangement do not exist in the real world.293 Even when the government can create a market for them, as it has done for college student loans, borrowers face substantial risks and the loans can be quite burdensome to pay. More direct public financing for early childhood care and education will lead to more investment in childrens’ development and thus more productive workers when the children are grown, while substantially easing families’ budgets in their early years of formation. A better-educated child also benefits the rest of society through reduced reliance on public support, productivity spillovers, and reduced criminal activity.

There is substantial precedent for extensive public involvement in this area. Most obviously, we provide free public education from age 5 onward. But those public investments are heavily tilted toward older children. President Barack Obama’s Council of Economic Advisers estimated (opens in a new tab) that, in 2015, combined annual local, state, and federal expenditure per child was 63 percent higher for those kids between the ages of 6 and 11 than for those between 3 and 5.294 This is despite the fact that evidence increasingly shows that high-quality early child care and childhood education, prior to entering Kindergarten, is a key investment with important implications for children’s long-run outcomes.295

There are a range of existing programs to help parents when children are very young. The Head Start preschool program is one example.296 But these programs are relatively small and tightly targeted to the very poor. The high expenses of early childhood are a burden not just for poor families but also for middle-class families, which are at similar risk of underinvesting in their young children. Another consequence of the high cost of early childhood care and education in private markets is that many families do not use it. This keeps parents, mostly mothers, out of the workforce, reducing family earnings and mothers’ career progression. Other families rely upon low-quality programs that do not adequately prepare children for school.

It is time to recognize that early child care and education is a public good and will be underprovided until it is treated as a public responsibility. We need greatly expanded public provision of child care and early childhood education, with public funding and careful, thoughtful regulation to ensure quality.297

Higher education

Higher education presents its own set of challenges. Extensive evidence demonstrates that high-quality higher education leads to enormous earnings increases and also delivers spillovers for more than just the students involved: Each young adult who is sent to college makes his or her neighbors and co-workers more productive as well.298 This type of externality, along with the same types of credit market failures discussed above that make it hard for children to borrow against their future earnings, leads to underinvestment by too many young adults and their families.

The United States currently supports higher education in three ways. We directly support public institutions of higher education through direct federal and state allocations; we provide grants to very low-income students; and we support public student loans. Yet all three of these policies are increasingly failing to keep up with changes in our economy.

There are not enough public colleges and universities to accommodate growing demand, even as higher education has become a near requirement for decent adult earnings. Scholarships for low-income students also are not keeping up with rising tuition and offer essentially no help with nontuition costs of higher education. And student loans are subject to abuse by low-quality institutions that take loans on students’ behalf without providing education of commensurate quality.299 This, of course, is risky for students who do not know if their education will pay off in terms of career success. Indeed, much of the growing student loan crisis (opens in a new tab) is concentrated among students who never finished their degrees.300

This is why policymakers need to take public action to reduce the private cost of higher education. This could take many forms, including increased spending on tuition subsidies, such as by expanding the existing Pell Grant program, and investing in a growing public higher education sector, with restrained or eliminated tuition made up through additional investment of tax revenue. The essential goal is to ensure that more affordable, high-quality spots are available for students wanting to pursue higher education, and that the cost burden on families of this pursuit is reduced.

Conclusion

Each of the above proposals—the social insurance programs we discussed first, as well as the  early childhood care, preschool, and higher education recommendations we presented second—would remove large costs and risks from families’ budgets. Together, they would allow earnings to go much further.

With these programs in place, families would not need to set aside substantial savings against the possibility of job losses, unexpected medical costs, an unanticipated long retirement, or a child who needs day care or college tuition. They could instead spend their earnings on meeting current consumption needs. Moreover, by removing social insurance benefits from employment relationships, these programs would free up constraints on the U.S. labor market, enabling better worker-job matching, higher female labor force participation, and thus higher productivity and wages.

We recognize that our proposals would require substantial additional federal budgetary commitments. It is important to recognize, however, that these are not new costs. They are merely transfers from families’ budgets to the government’s accounts. Because these types of public social insurance programs are much more efficiently provided at scale than at the individual level, the cost in increased taxes needed to finance them would be less than families are currently paying, allowing for increased consumption even after the higher tax bills are paid.

Moreover, the use of tax financing would enable more progressive funding structures that take account of the enormous increase in economic inequality that U.S. society and the economy have experienced in recent decades. This growing inequality means that even middle-class families increasingly need support to afford their obligations, and it makes sense for policymakers to draw on the extremely wealthy for disproportionate shares of the costs.

—Sandra E. Black is a professor of economic and international and public affairs at Columbia University. Jesse Rothstein is a professor of public policy and economics at the University of California, Berkeley.

Related

Your Direct Line to Cutting-Edge Research

Get updates on our latest research, event announcements, and policy insights delivered straight to your inbox. Stay connected with the leading voices on equitable growth.